Skip to content

Your Swiss tax return, prepared by an English-speaking tax advisor. First call free.

15 minutes on the phone to understand your tax situation and your needs.

No commitment · In English or French

Need a quote? It arrives within the hour after the call.

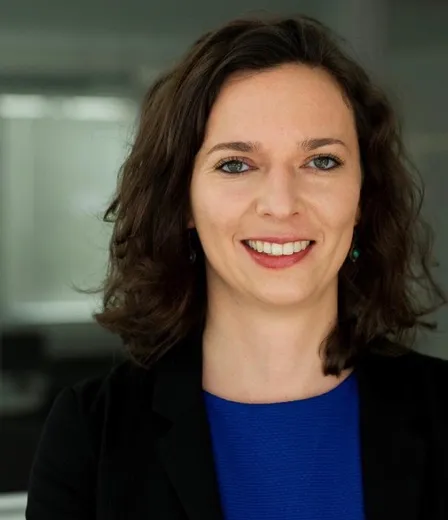
Ella Dettwiler Founder and tax advisor
See our services
  • 15+ years of experience
  • 1,000+ tax returns prepared
  • 7 cantons covered
  • Hosted in Switzerland
Ella Dettwiler - Founder, MyTaxAdvisor
Ella Dettwiler Founder and tax advisor

01 -Services

Our tax services

Expert guidance for every aspect of your taxation

Cross-Border Taxation

Cross-border workers are subject to complex tax rules arising from the double taxation agreements between Switzerland and France. Depending on your canton of employment, you may be taxed at source in Switzerland or only in France. We guide you to optimize your situation and avoid double taxation, taking into account the Franco-Swiss agreement of April 11, 1983 and its amendments.

New Arrivals & Expats

You have just moved to Switzerland and need to understand the Swiss tax system? We guide you from the moment you arrive to file your first tax return, choose your taxation regime, and identify applicable deductions from the very first year. We also explain how withholding tax works and the registration procedures with the cantonal tax authority.

Real Estate & Capital Gains

Real estate taxation in Switzerland includes capital gains tax on property (IBGI), imputed rental value, property tax, and wealth tax. We assist you during the purchase, ownership, or sale of property to optimize your tax burden. We precisely calculate deductions for maintenance costs, mortgage interest, and indirect amortization via pillar 3a.

Inheritance & Gifts

Inheritance and gift taxes vary considerably from one canton to another in Switzerland. Some cantons like Schwyz levy none at all, while others apply progressive rates that can reach 50% for non-relatives. We help you plan the transfer of your assets optimally, taking into account the spousal and direct descendant exemptions provided by cantonal legislation.

Retirement & Pension Planning

The Swiss pension system is built on three pillars: AHV/AVS (1st pillar), occupational pension LPP (2nd pillar), and tied individual pension (pillar 3a). Pillar 3a contributions are deductible from taxable income up to CHF 7,258 for employees affiliated with a 2nd pillar in 2026. We optimize your contributions, LPP buybacks, and staggered withdrawals to minimize the overall tax impact.

Crypto & Foreign Assets

In Switzerland, cryptocurrencies are considered wealth assets and must be declared at their value as of December 31, based on the rates published by the Federal Tax Administration. Capital gains realized by private investors are in principle exempt from tax, but trading activity deemed professional may be taxed as income. We also declare your foreign accounts and assets in compliance with legal obligations.

02 -Process

How it works

A simple process, 100% online

  1. 1

    Book a call

    Pick a slot online. A tax advisor calls you for a free 15-minute first consultation about your situation.

  2. 2

    Send your documents

    Securely transmit your tax documents through our encrypted platform. We guide you on what is needed.

  3. 3

    Tax return preparation

    Our tax expert analyzes your file, optimizes your deductions, and prepares your complete tax return.

  4. 4

    Review and submission

    You validate the finalized return. We submit it to the tax authority and handle the follow-up.

Ella Dettwiler - Founder MyTaxAdvisor

04 -Founder

Ella Dettwiler

Ella Dettwiler holds a Bachelor in Law and a Master in Public Law from the University of Geneva.

With over 15 years of experience in Swiss tax law, her career has been enriched through work in accounting and tax firms across the French-speaking part of Switzerland, from Geneva to Lausanne (canton of Vaud), where she has supported a wide range of clients through varied and complex tax situations.

Today, as founder of MyTaxAdvisor, she leverages her legal expertise and command of digital tools to deliver personalized, rigorous, and 100% digital tax guidance.

“Our role is not just to fill out a tax return, but to help you understand and master your tax situation.”
  • Absolute confidentiality
  • Transparency
  • Non-judgmental
  • Legal rigor
  • Personalized support
  • 100% digital

05 -Google reviews

What our clients say

They trusted us with their tax returns

5.0 / 5 Google rating · 2 reviews See the reviews on Google

Reviews translated by Google.

06 -FAQ

Frequently asked questions about Swiss tax returns

Everything you need to know about your Swiss tax return

What is the deadline for filing a tax return in Switzerland?
In Switzerland, the deadline for filing a tax return varies depending on the canton of residence. In most French-speaking cantons such as Geneva, Valais, Fribourg and Jura, the deadline is set at of the year following the tax period. The cantons of Vaud and Bern impose a shorter deadline of . The earliest is Neuchâtel: for the 2025 return, the exact date being printed on the form each year, with a free extension until . It is possible to request an extension from the cantonal tax authority, usually free of charge for a first postponement until . If the deadline is missed without requesting an extension, the taxpayer first receives a formal reminder, then risks a discretionary tax assessment based on an often unfavourable estimate of their income and assets.
What are the main tax deductions available in Switzerland?
Swiss taxpayers can benefit from numerous deductions to legally reduce their tax burden. The most significant include contributions to pillar 3a (up to CHF 7'258 in 2026 for employees affiliated with a 2nd pillar pension fund), voluntary buy-ins to the 2nd pillar (LPP/BVG), professional expenses (transport, meals), health insurance premiums and mortgage interest. Continuing education costs related to one's profession are deductible up to CHF 12'900 at the federal level, and third-party childcare costs up to CHF 25'500 per child at the federal level. Unreimbursed medical expenses are deductible in certain cantons beyond a threshold of 5% of net income. Donations to recognised public-benefit institutions are deductible up to 20% of net income.
How does withholding tax and the subsequent ordinary taxation (TOU) work in Switzerland?
Withholding tax in Switzerland applies to foreign employees holding a B, L or G permit (cross-border commuters), as well as certain other categories of taxpayers. The employer deducts the tax directly from the salary according to a schedule that takes into account family status, number of children and the canton of employment. Since the reform that came into effect on , taxpayers subject to withholding tax whose gross income exceeds CHF 120'000 per year are automatically subject to a subsequent ordinary taxation (TOU - Taxation Ordinaire Ultérieure). Others may voluntarily request it before of the following year if significant deductions are not accounted for by the withholding schedule. The TOU is now irrevocable and allows the taxpayer to claim all deductions as an ordinarily assessed taxpayer.
What are the tax obligations for cross-border commuters in Switzerland?
The tax obligations for cross-border commuters depend primarily on the canton of employment and the applicable double taxation agreement. Cross-border workers employed in Geneva or Fribourg, cantons that are not party to the 1983 agreement, are subject to withholding tax in Switzerland, whereas those working in the cantons of Vaud, Valais, Neuchâtel, Bern, Jura, Solothurn and Basel are taxed in France under the Franco-Swiss agreement of , with financial compensation paid to the cantons. Cross-border commuters subject to withholding tax in Switzerland should check whether a TOU (subsequent ordinary taxation, i.e. filing a full tax return) would be advantageous, particularly for quasi-resident status in Geneva. All cross-border commuters must also declare their income in France, where a tax credit or exemption with progression applies depending on the canton. It is crucial to fully understand these rules to avoid any risk of double taxation. Discover our cross-border tax service.
How do I declare cryptocurrencies on my Swiss tax return?
In Switzerland, cryptocurrencies (Bitcoin, Ethereum, etc.) are considered movable assets and must be declared on the tax return at their value as of . The Federal Tax Administration (FTA) publishes an official exchange rate each year for the main cryptocurrencies, which serves as a reference for valuation. For private investors, capital gains realised on cryptocurrencies are in principle tax-exempt, but income from staking, mining or lending constitutes taxable income. Caution: trading activity deemed professional by the tax authorities (high volume, frequent transactions, use of leverage, debt financing) results in capital gains being taxed as self-employment income, plus AHV/AVS social contributions. Tokens received via airdrop or as compensation are also taxable as income at their value upon receipt.
Show more questions (9)
How much can you deduct with the 3rd pillar (pillar 3a) in Switzerland?
Pillar 3a is one of the most powerful tax deduction instruments in Switzerland. In 2026, the maximum deductible amount is CHF 7'258 for employees and self-employed individuals affiliated with a 2nd pillar pension fund. For self-employed individuals without a 2nd pillar, the ceiling is 20% of net earned income, up to a maximum of CHF 36'288. For 2027, these limits rise to CHF 7'373 and CHF 36'864. Contributions to pillar 3a are fully deductible from taxable income at the federal, cantonal and municipal levels. The accumulated capital is locked until five years before retirement age, except in the case of purchasing a primary residence, permanently leaving Switzerland or becoming self-employed. Upon withdrawal, the capital is taxed separately from current income at a reduced rate. To optimise the tax treatment at withdrawal, it is advisable to spread your 3a savings across multiple accounts and withdraw them in different tax years.
What documents are needed to complete a tax return in Switzerland?
To correctly complete a tax return in Switzerland, you need to gather several categories of documents. Income-related documents include the salary certificate, AHV/IV (AVS/AI) pension statements, unemployment or loss-of-earnings insurance statements, and securities income certificates. For assets, you need bank statements as of , redeemable life insurance policies, vehicle valuations and property appraisals. Supporting documents for deductions include pillar 3a certificates, donation receipts, invoices for unreimbursed medical expenses, childcare cost certificates and proof of continuing education expenses. Property owners must also provide the mortgage interest statement and invoices for maintenance work. All of these documents allow your tax advisor to optimise your return by identifying all applicable deductions.
How can I optimise my tax return in French-speaking Switzerland?
Tax optimisation in French-speaking Switzerland involves several complementary legal strategies. First, maximise your pillar 3a contributions each year (CHF 7'258 in 2026 for employees) and consider voluntary buy-ins to the 2nd pillar if your pension fund allows it. Second, systematically declare all actual professional expenses if they exceed the flat-rate deduction: commuting costs, meals away from home, continuing education, professional tools. Third, for property owners, alternate between the flat-rate and actual maintenance costs depending on the year, and group renovation work within the same tax period to maximise the effect of deductions. Fourth, check eligibility for a TOU (subsequent ordinary taxation, i.e. filing a full tax return) for taxpayers subject to withholding tax and apply for quasi-resident status in Geneva if the conditions are met. Finally, plan capital withdrawals from the 2nd pillar and pillar 3a over several tax years to limit the impact of progressive tax rates. Our experts can guide you through this process.
What are the consequences of late filing of a tax return?
Failure to meet the filing deadline for a tax return in Switzerland triggers a graduated procedure. The tax authority first sends a free reminder or a formal summons accompanied by a fee (generally between CHF 40 and CHF 100 depending on the canton). If the taxpayer does not respond despite the summons, the authority proceeds with a discretionary tax assessment, meaning it estimates the taxpayer's income and assets itself, often unfavourably. A discretionary assessment can be contested within 30 days, but the taxpayer must then prove that the estimate is manifestly incorrect. Additionally, a fine for non-filing of up to CHF 10'000 may be imposed in cases of repeated offences or serious non-compliance. It is therefore strongly recommended to request a deadline extension rather than failing to file your return.
How does income splitting work for married couples in Switzerland?
In Switzerland, married couples are jointly taxed on all their income and assets, which can result in a higher tax burden due to the progressive tax rate structure. To mitigate this effect, most cantons and the Confederation apply a corrective measure: at the federal level, taxable income is divided by a factor of 1.8 (partial splitting) to determine the applicable rate. The French-speaking cantons have their own mechanisms: a specific tax schedule for couples, full or partial splitting, or a dual-income deduction. The situation for dual-income couples is often disadvantaged compared to two unmarried individuals (the so-called marriage penalty), a topic regularly debated in Parliament.
What happens if I don't declare my cryptocurrencies?
Failing to declare your cryptocurrencies constitutes tax evasion and is subject to penalties. Thanks to the Automatic Exchange of Information (AEOI) and the growing cooperation between exchange platforms and tax authorities, the risk of detection increases every year. If discovered, the tax authority can issue a back-tax assessment covering the last 10 years, plus default interest (3-5% per year) and fines of up to 3 times the evaded tax. A voluntary self-disclosure allows you to avoid the criminal fine (only once in a lifetime), but back-tax assessments and interest remain due. It is therefore strongly advised to regularise your situation as soon as possible.
How do I declare a foreign property on my Swiss tax return?
Swiss taxpayers must declare all their real estate, including properties located abroad. Foreign property is declared as an asset at its fair market value, and rental income or imputed rental value is added to income. However, under double taxation agreements, the property is generally taxed in the country where it is located. In Switzerland, it is taken into account only to determine the tax rate applicable to the remaining income and assets (progression reservation). Mortgage interest and maintenance costs related to the foreign property are deductible proportionally. It is essential to correctly complete the annex relating to foreign real estate to avoid double taxation.
How does taxation work for the self-employed and freelancers in Switzerland?
Self-employed workers and freelancers in Switzerland are subject to a specific tax regime. Net income from self-employment (revenue minus expenses) is taxed as ordinary income, plus AHV/IV/EO (AVS/AI/APG) social contributions calculated on this income (between 5.371% and 10% depending on the amount). Self-employed individuals can deduct all justified professional expenses: office space, equipment, professional vehicle, insurance, professional dues and depreciation. They benefit from an increased pillar 3a ceiling (20% of net income, max CHF 36'288 in 2026) if they are not affiliated with a 2nd pillar pension fund. Proper bookkeeping is mandatory above CHF 500'000 in revenue. See our complete guide for the self-employed.
Do you offer services for businesses (legal entities)?
MyTaxAdvisor specialises in personal taxation: tax returns, withholding tax, TOU (subsequent ordinary taxation, i.e. filing a full tax return), pension planning, real estate and inheritance. For legal entities (SA, Sàrl, associations, foundations), we work in partnership with MyBusinessAdvisor, an accounting and tax firm specialising in accounting, taxation and business management in French-speaking Switzerland. Through this partnership, we ensure comprehensive coverage of your tax needs, whether you are an individual or a business owner.

07 -Contact

Contact us

Let’s discuss your tax situation

+41 76 200 80 74
Monday, Tuesday, Thursday and Friday: 9am - 12pm and 2pm - 6pm. Closed on Wednesdays.
Geneva, Vaud, Valais, Fribourg, Neuchâtel, Bern, Jura

Free 15-minute call. You pick the time. No commitment.